Fixing yfinance 429 Rate Limits & Broken Options Chains in Python
Replace brittle HTML/crumb scrapers with deterministic REST & WebSocket endpoints, batched multi-symbol quotes, and analytical Black-Scholes options Greeks.
Unofficial Yahoo Finance scrapers (yfinance, yahoo_fin) rely on rotating session cookies and undocumented web endpoints. In production Python jobs, scheduled cron pipelines, or shared cloud IPs, they frequently fail with HTTPError: 429 Too Many Requests, missing fundamental fields, or empty options DataFrames when upstream HTML layouts change.
This guide shows how to migrate common yfinance workflows—batched quotes, historical OHLCV bars, technical indicators, and options chains with Greeks—to the normalized ApexTick REST & WebSocket Data API in under five minutes.
Why Unofficial Scrapers Break in Production
| Failure Mode | Unofficial Scraper (yfinance) | ApexTick Data API |
|---|---|---|
| Rate limiting on cloud/VPS IPs | Frequent 429 Too Many Requests or silent crumb blocks on AWS, GCP, Hetzner, and GitHub Actions. | Authenticated API key quotas (10/min Hobbyist up to 3,000/min Enterprise) with predictable daily limits. |
| Multi-symbol watchlists | Sequential per-ticker HTTP scraping or fragile multi-threading. | Single batched call: GET /v1/market/quotes?symbols=AAPL,MSFT,NVDA,SPY (up to 50 symbols per request). |
| Options Greeks (`Delta`, `Gamma`, `Theta`, `Vega`) | Not provided (only raw bid/ask and sporadic implied volatility). | Analytical Black-Scholes Greeks (iv, delta, gamma, theta, vega, rho) computed on every option contract. |
| Technical indicators | Requires downloading full history and computing locally with pandas-ta or TA-Lib. | Server-computed rsi14, sma20/50/200, macd, atr14, volatility30, and rvol20 in one call. |
| AI Assistant & Excel support | Requires custom wrapper scripts. | Native 8-tool MCP Server and 17-function Excel Add-ins. |
1. Side-by-Side Migration: Batched Multi-Ticker Quotes
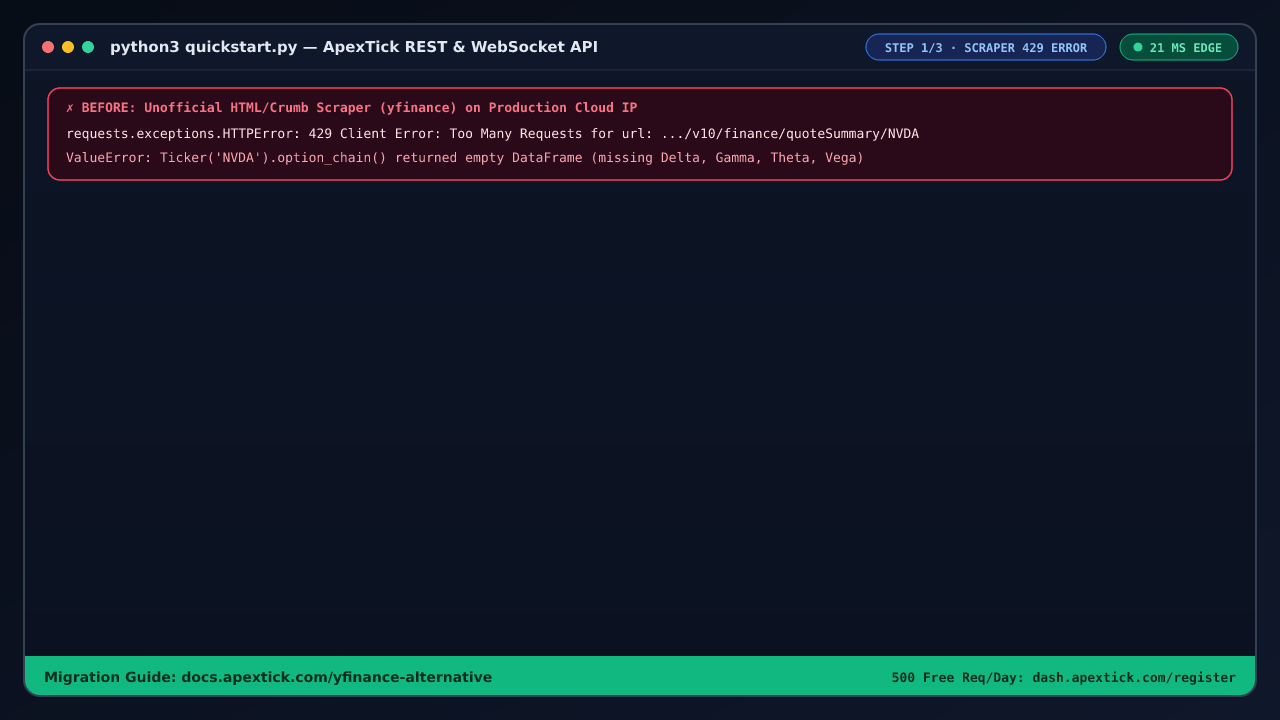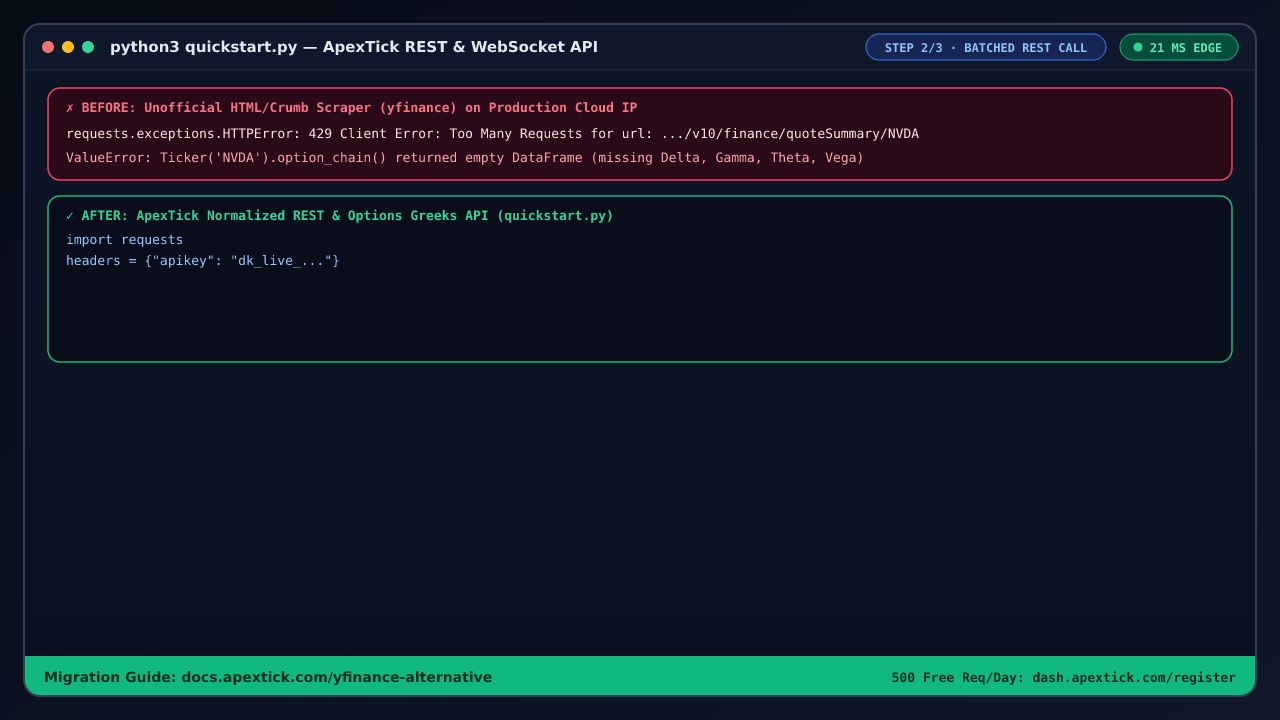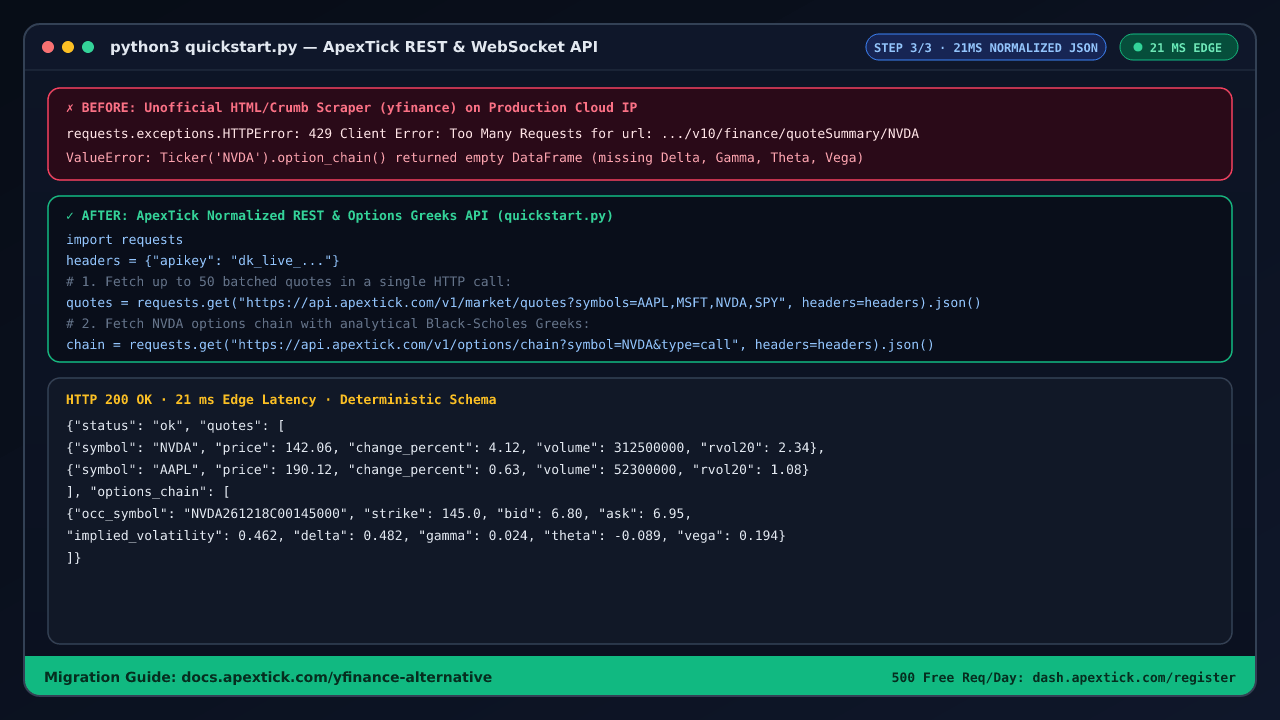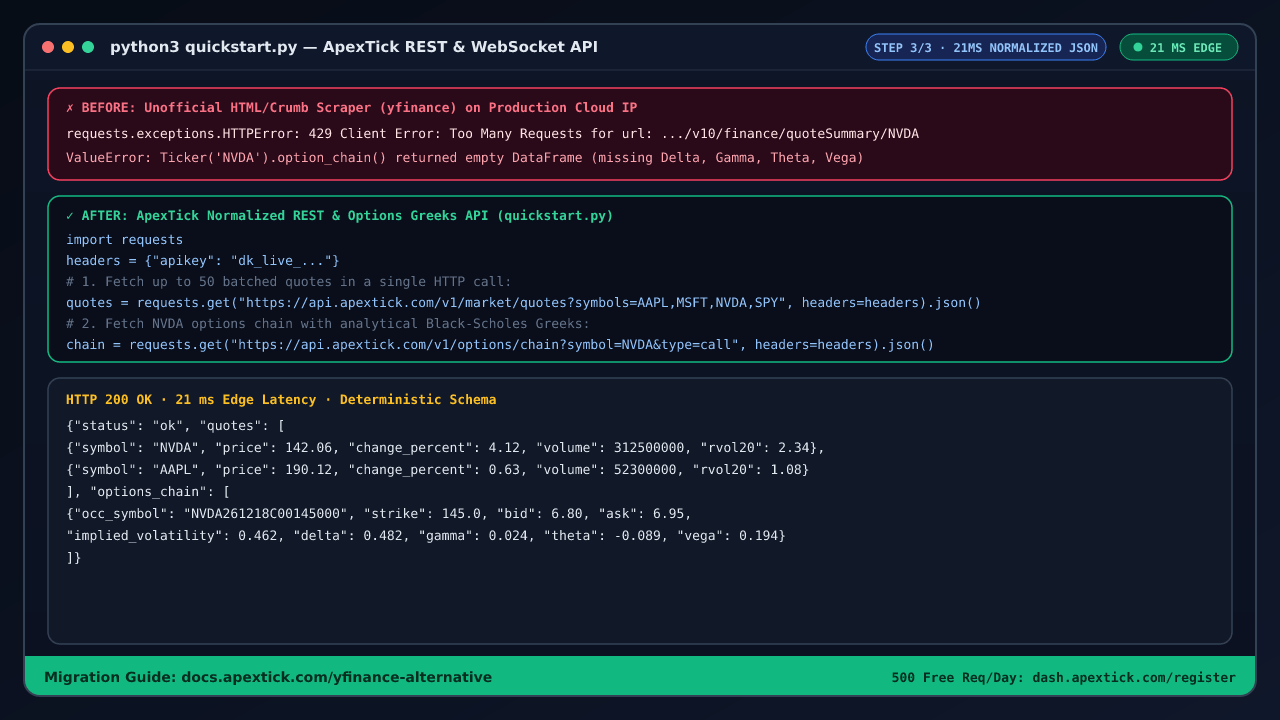
Instead of looping over yf.Ticker(sym).info (which triggers multiple HTML/JSON scrape requests per symbol), fetch up to 50 normalized quotes in a single HTTP request:
import os
import requests

API_KEY = os.environ["APEXTICK_API_KEY"]  # Get a free key at https://dash.apextick.com/register
BASE_URL = "https://api.apextick.com"

resp = requests.get(
    f"{BASE_URL}/v1/market/quotes",
    params={"symbols": "AAPL,MSFT,NVDA,SPY,BTC-USD"},
    headers={"apikey": API_KEY},
    timeout=10,
)
resp.raise_for_status()

for q in resp.json()["data"]:
    print(f"{q['symbol']:8s}  ${q['price']:>8.2f}  ({q['change_percent']:+.2f}%)  vol={q['volume']:,}")
2. Historical OHLCV Candles Directly into a pandas.DataFrame
GET /v1/market/candles returns clean, split-adjusted OHLCV bars (1m, 5m, 15m, 30m, 1h, 1d, 1wk, 1mo) with standard ISO-8601 / Unix timestamps:
import pandas as pd
import requests

resp = requests.get(
    "https://api.apextick.com/v1/market/candles",
    params={
        "symbol": "NVDA",
        "resolution": "1d",
        "from": "2026-01-01",
        "to": "2026-11-01",
    },
    headers={"apikey": API_KEY},
    timeout=10,
)
resp.raise_for_status()

df = pd.DataFrame(resp.json()["data"])
df["time"] = pd.to_datetime(df["timestamp"], unit="s", utc=True)
df = df.set_index("time")[["open", "high", "low", "close", "volume"]]
print(df.tail())
3. Options Chains with Analytical Black-Scholes Greeks
One of the most common pain points with yfinance is Ticker("NVDA").option_chain(), which lacks Delta, Gamma, Theta, and Vega and frequently returns 0.0 or NaN for implied volatility outside regular session hours.
ApexTick's GET /v1/options/chain and GET /v1/options/screener return complete contract pricing alongside analytical Black-Scholes Greeks:
resp = requests.get(
    "https://api.apextick.com/v1/options/chain",
    params={"symbol": "NVDA", "type": "call"},
    headers={"apikey": API_KEY},
    timeout=10,
)
resp.raise_for_status()

contracts = pd.DataFrame(resp.json()["data"])
cols = ["occ_symbol", "strike", "expiration", "bid", "ask", "implied_volatility", "delta", "gamma", "theta", "vega"]
print(contracts[cols].head(10))
4. Live Event-Driven WebSocket Streaming
Instead of polling HTTP endpoints in a while True loop, subscribe to /v1/market/stream over WebSocket. You receive an immediate state snapshot upon subscription followed by monotonically ordered trade updates:
import asyncio
import json
import websockets

async def stream_quotes():
    uri = "wss://api.apextick.com/v1/market/stream"
    headers = {"apikey": API_KEY}
    async with websockets.connect(uri, additional_headers=headers) as ws:
        await ws.send(json.dumps({"action": "subscribe", "symbols": ["AAPL", "NVDA", "BTC-USD"]}))
        async for msg in ws:
            event = json.loads(msg)
            print(event)

asyncio.run(stream_quotes())
Create an account at dash.apextick.com/register to get an instant dk_… API key with 500 requests per UTC day at $0/mo (no credit card required).